FOR IMMEDIATE RELEASE
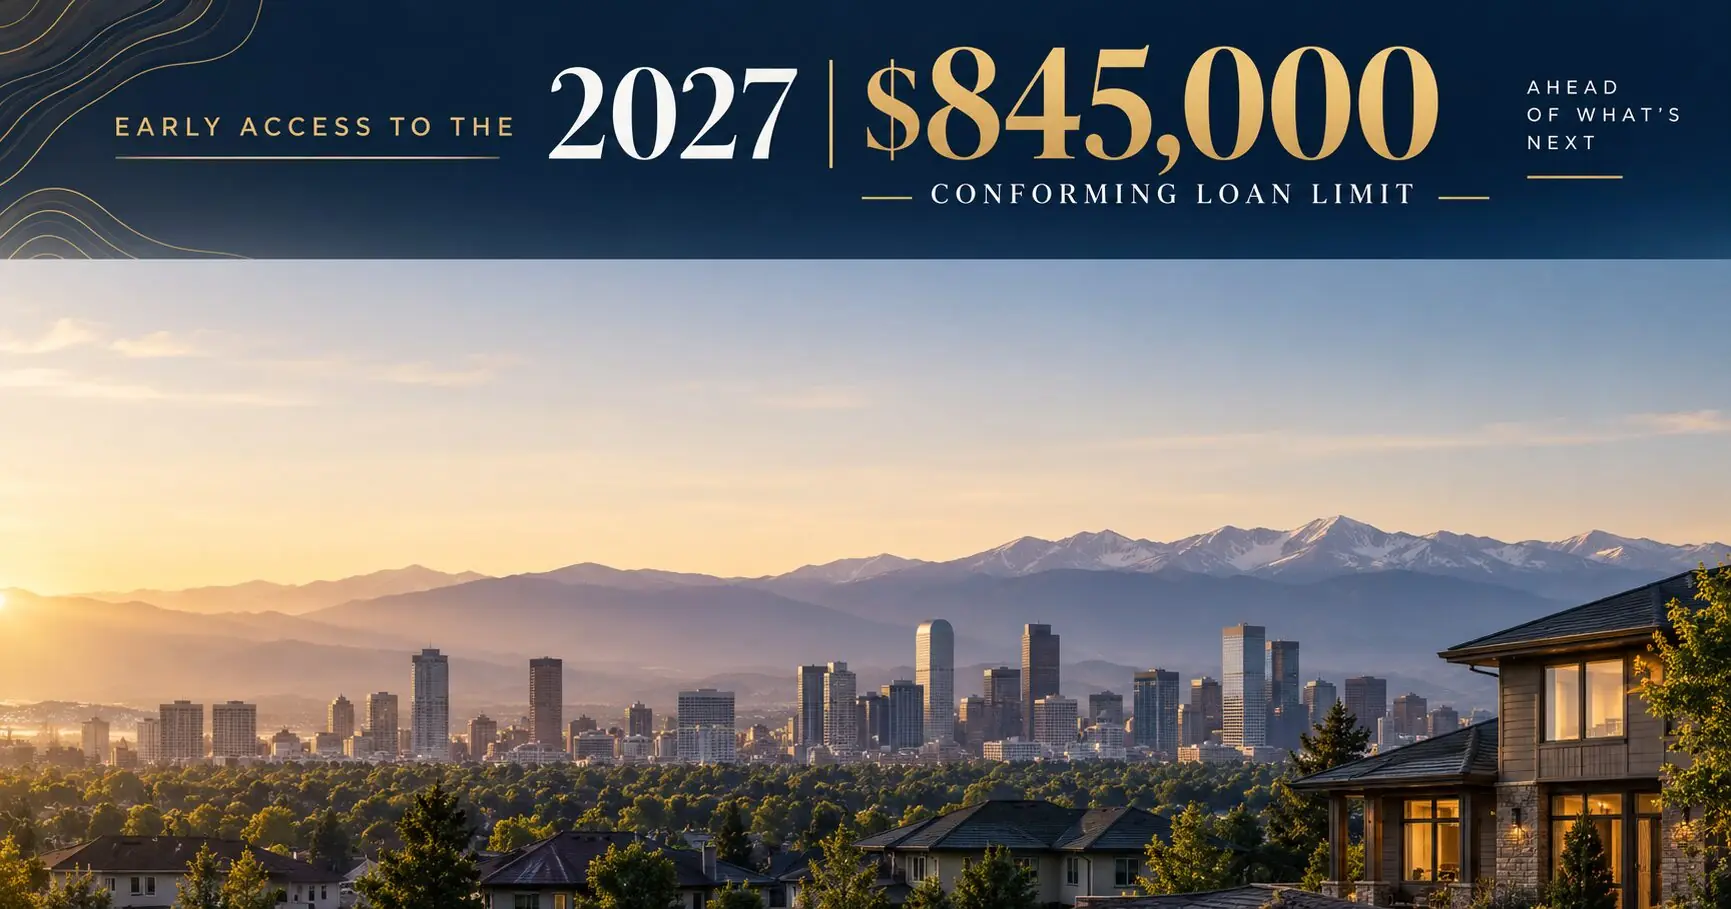
DENVER, CO, September 16, 2026. Mortgage Maestro Group, an independent, veteran-owned mortgage brokerage serving Colorado and four other states, announced today that eligible clients can now access financing at the 2027 conforming loan limit of $845,000 for one-unit homes, months ahead of the Federal Housing Finance Agency’s (FHFA) official baseline announcement expected in November.
What the 2027 Conforming Loan Limit Means for Buyers
Each November, the FHFA sets the baseline conforming loan limit, the maximum loan size Fannie Mae and Freddie Mac can purchase, based on year-over-year changes in national home prices. The current 2026 baseline sits at $832,750 for most of the country. Several lending partners in Mortgage Maestro Group’s network have already moved to a $845,000 limit for 2027, a 1.47% increase, ahead of FHFA’s own confirmation.
That early move matters because loans within the conforming limit are eligible for sale to Fannie Mae and Freddie Mac, which typically means better pricing and more flexible terms than a jumbo loan carries. A buyer whose loan amount now falls under $845,000, where it would have exceeded the 2026 cap, may qualify for conventional financing today instead of waiting on a jumbo product or waiting for FHFA’s official update.
“Waiting until November to give clients this advantage never made sense to us,” said Ray Williams, President of Mortgage Maestro Group. “Our clients aren’t waiting on a government calendar to buy a home, so we work with lending partners who move first and pass that along immediately.”
Because Mortgage Maestro Group is an independent brokerage rather than a single direct lender, clients aren’t limited to one company’s early decision. We compare terms across the lending partners in our network who have already implemented the increase, the same approach we use on every file. See our guide to why the person guiding your financing matters as much as the numbers for more on that process. Availability, exact pricing, and high-cost county limits vary by lending partner and will be confirmed against FHFA’s official figures once published in November.
How This Affects VA Loan Borrowers
Veterans with full VA entitlement already have no VA-imposed loan cap and haven’t since 2020, so this change doesn’t add a ceiling that wasn’t there before for most VA borrowers. Where it does matter is for veterans using remaining or partial entitlement, most often someone carrying a prior VA loan while purchasing again. For that group, the maximum no-money-down guaranty is tied directly to the county conforming loan limit, so an early move to $845,000 expands zero-down purchasing power right now rather than in November. Our VA home loan basics guide walks through how full and partial entitlement work in more detail.
Conforming vs. Jumbo: Why the Limit Matters
A loan that falls within the conforming limit is generally priced and underwritten differently than a jumbo loan, which exceeds it. Conforming loans are eligible for Fannie Mae and Freddie Mac purchase, which usually means more competitive rates and more standardized documentation than jumbo financing requires. Our guide to conventional fixed-rate mortgages in Denver covers how conforming pricing works for buyers weighing a conventional loan against jumbo alternatives. FHFA’s own FHFA’s 2026 conforming loan limit announcement details how the annual adjustment is calculated and how high-cost counties are treated differently from the baseline.
Frequently Asked Questions
What is the 2027 conforming loan limit?
Several of Mortgage Maestro Group’s lending partners have set their 2027 conforming loan limit at $845,000 for one-unit homes in most counties, a 1.47% increase over the 2026 baseline of $832,750. FHFA’s official 2027 baseline will be confirmed in November.
Can I get a loan at the new limit before FHFA’s official announcement?
Yes, through lending partners in Mortgage Maestro Group’s network who have already adopted the higher limit. Eligibility, pricing, and exact terms depend on the individual lender’s guidelines until FHFA’s official figures are published.
How does the higher limit affect VA loan borrowers?
Veterans with full entitlement already have no VA-imposed cap. Veterans using partial or remaining entitlement have their zero-down guaranty tied to the county conforming loan limit, so a higher limit increases their no-money-down purchasing power immediately.
What’s the difference between a conforming loan and a jumbo loan?
A conforming loan falls within the limit Fannie Mae and Freddie Mac will purchase and typically carries more competitive pricing and standardized underwriting. A jumbo loan exceeds that limit and usually comes with stricter qualification requirements and different pricing.
What happens if FHFA’s official 2027 limit is different from $845,000?
Terms would be adjusted to match FHFA’s confirmed baseline once it’s published in November. Mortgage Maestro Group will update clients directly if a file is affected.
Should I wait for FHFA’s official November announcement before making an offer?
No, waiting costs more than it protects. If you wait until November to see FHFA’s confirmed number, you have spent two to three months shopping with a smaller number in your head, potentially walking away from homes that were actually in range. Lock in a pre-approval reflecting the $845,000 limit now through a lending partner who has already adopted it. If FHFA’s official figure lands somewhere else, your terms get adjusted to match. The downside risk of moving early is minimal; the downside of waiting is losing houses to buyers who did not wait.
Does a higher conforming loan limit actually lower my monthly payment?
Only if your loan amount would have exceeded the old limit. The limit itself does not change your interest rate or payment on a loan that already fit inside the 2026 cap of $832,750. What it changes is which loans qualify as conforming instead of jumbo. If your loan amount falls between $832,750 and $845,000, moving from jumbo to conforming financing typically means a better rate and looser documentation requirements, which does lower your payment. Run your specific loan amount against both limits before assuming this helps you.
I already have a jumbo quote from another lender. Does this change anything for me?
It might, and it is worth a second look before you sign anything. If your loan amount sits under $845,000, a jumbo quote you received before this increase may no longer be your best option. Bring your existing quote to Mortgage Maestro Group and we will compare it against conforming pricing at the new limit, the same second opinion review we run for any borrower questioning a quote already in hand.
Does this change how aggressively I should offer on a competitive listing?
It can, but only if you confirm your number before you are in a bidding situation, not during one. A buyer whose maximum loan amount just moved from $832,750 to $845,000 has roughly $12,250 in additional financed purchasing power, assuming the rest of their qualification holds. That is not license to stretch your budget; it is information to have settled before you are competing for a home, so your offer reflects what you can actually close, not what you hope you can close.
Does the $845,000 limit apply the same way everywhere I might buy?
No. $845,000 is the baseline limit for most counties nationwide, but high-cost counties, including several in Colorado’s mountain and resort corridors, carry higher ceilings tied to local home prices. If you are shopping outside the Denver metro, confirm the specific limit for the county where you are buying rather than assuming the baseline number applies. FHFA’s FHFA’s conforming loan limit map lets you look up the exact limit for your county.
What should I actually do before my next offer?
Get a pre-approval that reflects the $845,000 limit rather than the 2026 number you may have been quoted earlier this year. If your last pre-approval is more than a few months old, or came from a lender who has not confirmed adoption of the new limit, it may understate what you actually qualify for or misstate whether you land in conforming or jumbo territory. A five minute conversation before you write an offer is cheaper than finding out after you are under contract.
Get Pre-Approved at the 2027 Limit Now
If a higher loan amount changes what you can offer on your next home, or if you’re a veteran using partial entitlement on a second VA purchase, don’t wait for FHFA’s November announcement to find out where you stand. Contact Mortgage Maestro Group for a pre-approval that reflects the 2027 conforming loan limit today. Call 303-779-0591 or visit mortgage-maestro.com.
Mortgage Maestro Group, NMLS #1838215, 387 N Corona St #646, Denver, CO 80218, is a veteran-owned, independent mortgage brokerage licensed in Colorado, California, Wyoming, Texas, and Florida. Equal Housing Opportunity.
About Mortgage Maestro Group
Founded in February 2019 by U.S. Navy veteran Ray Williams, Mortgage Maestro Group is an independent mortgage brokerage headquartered in Denver, Colorado, serving purchase, refinance, VA, investment property, and non-QM borrowers across five states. The company’s mission is to treat every mortgage as if it is its own.
Media Contact:
Ray Williams, President
Mortgage Maestro Group
303-779-0591
mortgage-maestro.com
###