Vet a Denver condo HOA the way an underwriter will: request the budget, the reserve study, the litigation disclosure, and recent meeting minutes before you go under contract. A weak association can cost you the loan, the resale value, or both. The unit is the easy part of the approval. The building is the part that surprises people.
The lender approves the building, not only the buyer
On a single-family purchase, the file is about you: income, credit, assets, the appraisal. On a condo purchase, there is a second borrower in the room, and it is the association. Lenders review the project itself, and a project can fail underwriting for reasons that have nothing to do with your qualifications.
Four of the common ones: pending litigation involving the association, an underfunded reserve account, too high a percentage of investor-owned units, or a single owner holding too many units in the building. Any of those can move a project from financeable to not financeable, and none of them show up on your credit report.
That is why the vetting has to happen early. A buyer who waits for underwriting to request association documents is finding out in week three of a thirty day contract whether the building works. A buyer who asks for those documents before signing is making the same decision with all of the leverage and none of the earnest money at risk.
What does warrantable mean, and why does it decide your financing?
A warrantable condo meets Fannie Mae and Freddie Mac project standards, which means it can be financed conventionally. A non-warrantable condo cannot. Buyers in a non-warrantable project need portfolio or non-QM financing, which typically means a larger down payment and higher pricing than a conventional loan on the same unit.
Projects commonly go non-warrantable for active litigation, investor concentration, inadequate reserves, too much commercial space in the building, delinquent dues above a threshold, or single-entity ownership concentration where one party owns an outsized share of the units.
Here is the part most buyers never think about. Warrantability is not a one-time test you pass at closing. It is a condition of the building, and it can change while you own the unit. If the project loses warrantability three years in, your buyer pool narrows to people with cash or portfolio money, and your exit becomes materially harder than your entry was. The purchase consequence is a pricing problem. The resale consequence is a liquidity problem, and that one is bigger.
Which documents should you request before you go under contract?
Ask for these four in writing, through your agent, as early as the seller will produce them:
- The HOA budget. This shows what the association collects and what it spends, including the line item going to reserves.
- The reserve study. This is the association’s own engineering assessment of what the building’s major components cost to replace and when. If there is no reserve study at all, that is information too.
- The litigation disclosure. Any pending or threatened legal action involving the association, which is the single fastest way a project becomes unfinanceable.
- Recent meeting minutes. Minutes are where the roof conversation, the balcony conversation, and the special assessment conversation actually happen, usually months before any of it reaches a disclosure form.
Read the minutes last and read them closely. Budgets tell you what the association planned. Minutes tell you what the owners are arguing about.
How do you read an HOA budget the way an underwriter does?
Find the reserve contribution line and compare it to the total annual budget. As a rough benchmark, lenders performing a full project review generally want to see at least 10 percent of the annual budget going to reserves. That is the number to anchor on when you open the budget for the first time.
An association contributing well under that figure is running on current dues, which works right up until something expensive breaks. Then the repair is not covered by savings, so it becomes a special assessment, and special assessments land on owners in amounts that have nothing to do with what they budgeted for housing.
Cross-check the reserve balance against the reserve study. If the study says the roof has eight years left and costs a number the association does not have and is not on pace to have, you are looking at a future assessment with a date attached to it. Dues that look attractively low today are frequently the reason the reserve line is thin, and low dues plus a thin reserve is not a bargain. It is a deferred bill.
Why Colorado’s construction-defect history makes older attached housing harder
Colorado has a long construction-defect litigation history in attached housing, and the practical result is that older condo and townhome projects across the Denver metro get scrutinized hard. Underwriters look at litigation disclosures for these projects with an attentiveness they do not apply to a detached home in the same zip code.
This shows up everywhere along the Front Range: converted lofts in LoDo and RiNo, 1970s and 1980s buildings in Capitol Hill and Glendale, garden-style complexes in Aurora and Lakewood, and newer attached product in the northern suburbs. Age alone does not disqualify a project, and plenty of older Denver buildings are beautifully run. But if you are shopping attached housing here, assume litigation history is a question your lender will ask, and get the answer before you are emotionally committed to the unit.
Worth knowing: litigation does not have to be a defect case to matter. An association suing a vendor, or being sued by an owner, can still stall a conventional approval until the file clarifies what the action involves.
What to look for when you walk the building
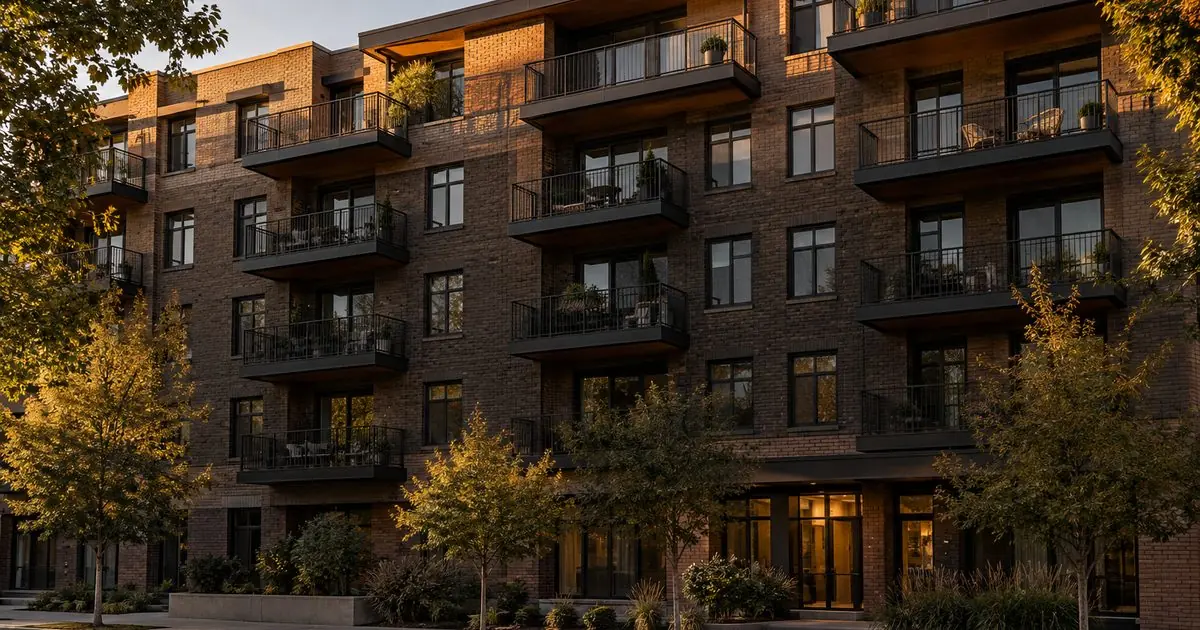
Documents tell you one story. The building tells you another, and you can read it without any technical training. Walk the property with your agent and look at the components that cost the most to replace:
- Roof. Sagging, patching, visible age, or any conversation about it in the minutes.
- Windows. Fogging between panes, failed seals, rot at the frames. Windows tend to fail as a generation, not one at a time.
- Balconies and decks. Rust at the connections, soft wood, temporary bracing, or caution tape.
- Parking structure. Spalling concrete, exposed rebar, standing water, active shoring.
Deferred maintenance a buyer can see is deferred maintenance an appraiser and an underwriter can see too. If the association has not funded the fix, the fix becomes an assessment, and the assessment lands on whoever owns the unit when the vote passes. That could easily be you.
The investor who read the building and walked away
A buyer was purchasing a condo as an investment. He asked for the HOA financials up front rather than waiting for underwriting to request them. He had also noticed problems with the windows in the unit he was buying, and he reasoned that if these windows were failing, the windows in the rest of the building probably were too, which is a special assessment waiting to happen.
When the financials arrived, the association was self-managed and running vapor thin on reserves. The existing owners were evidently comfortable with that. He was not.
His reasoning went like this. With no reserves, every future repair becomes a special assessment. Assessments push monthly dues up sharply. A building with climbing dues and visible deferred maintenance can lose its warrantability, at which point conventional financing dries up for everyone in it. Future buyers then need cash or portfolio money, the pool of people who can purchase your unit shrinks, and your exit becomes much harder than your entry was.
He cancelled the contract and bought a different property. Nobody denied his loan. He read the building correctly and declined to own the problem. That is the whole skill, and he applied it before his earnest money was at risk rather than after.
Why the HOA is usually the slowest part of a condo closing
Condo files require documents only the association can produce: the project questionnaire, the budget, the operating income statement, reserve figures, and insurance certificates. Your lender cannot generate any of it and cannot substitute anything for it.
The management company has no stake in your closing. They are not a party to the deal and they are not paid faster if you close on time. Most route these requests through a third-party document portal rather than handling them directly, which adds a queue between your lender and the person who actually has the information.
When information comes back incomplete or contains an error, it does not get fixed in a phone call. The request goes back through the queue for corrected documents. One transposed number can cost the better part of a week, and that week comes out of your contract timeline, not theirs. None of this is a reflection of how hard anyone on your side is working. It is the structure of who holds the paper.
What the status letter is, and why it arrives the day before closing
The status letter is the association’s statement of what you owe at closing: prorated dues, transfer or working capital fees, and any assessment in place. The title company cannot finalize the settlement statement without it.
It routinely arrives the day before closing. Which means a buyer who wants their final wire amount with enough time to actually move the money is waiting on a document the lender neither controls nor can accelerate. The lender ends up looking slow for something they did not do and cannot fix.
Plan for it. If you are wiring funds from an account with transfer limits, or from an institution that holds large outgoing wires for review, tell your loan officer and your title company early so they can work with an estimated figure and you are not scrambling the afternoon before you sign.
How to protect your timeline on a Denver condo purchase
Two things help. First, build extra days into the contract. A condo purchase is not a single-family purchase with a smaller yard, and a timeline that works for a detached home in Arvada will be tight for a converted loft downtown.
Second, get both agents pushing on the association alongside the lender. A listing agent chasing their own seller’s closing often gets a faster response from a management company than a lender does, because the association recognizes the seller as an owner and the lender as a stranger. It is still a third party nobody can compel, so more people asking politely and persistently is the only real lever anyone has.
Ask your lender at the very beginning of the process whether they have ordered the project review and what is outstanding. A condo file where the association documents were requested on day two is a different file from one where they were requested on day fifteen.
“The unit is the easy part. If the association is broke, you are buying a share of being broke, and no amount of loving the kitchen fixes that.”
Ray Williams
President, Mortgage Maestro Group
Related reading
- the real cost of buying in a Denver metro district
- how a file gets denied after conditional approval
- how fast a broker can rescue a denied loan
Fannie Mae publishes the condo project standards lenders apply at singlefamily.fanniemae.com.
Frequently asked questions about vetting a Denver condo HOA
What makes a condo non-warrantable?
A condo project is non-warrantable when it fails Fannie Mae or Freddie Mac project standards. Common causes include active litigation involving the association, a high percentage of investor-owned units, inadequate reserve funding, too much commercial space in the building, owner dues delinquencies above a set threshold, and single-entity ownership concentration where one party owns too many units. Any one of these can block conventional financing for the entire project, not just one unit.
How do I find out if an HOA has pending litigation?
Request the association’s litigation disclosure in writing through your agent, and read the last twelve months of board meeting minutes. Minutes often reference legal matters before any formal disclosure is updated. The management company or the board secretary is the source. Ask specifically about pending, threatened, and recently settled actions, since a matter that just closed can still affect how an underwriter reviews the project.
Can you get a mortgage on a non-warrantable condo?
Yes, through portfolio or non-QM financing rather than a conventional loan. These programs exist specifically for projects that do not meet agency standards. Expect a larger down payment requirement and higher pricing than a conventional loan on a comparable unit. The bigger consideration is resale: the next buyer faces the same limited financing options, which shrinks the pool of people who can purchase your unit later.
What is a healthy reserve level for a condo HOA?
As a rough benchmark, lenders performing a full project review generally want to see at least 10 percent of the annual budget going to reserves. Compare that contribution line against the association’s reserve study, which lists what major components cost to replace and when they are due. A budget meeting the 10 percent mark but facing a roof replacement next year is still thin. Read both documents together.
Can a special assessment be passed after I buy the condo?
Yes. An association can approve a special assessment at any point under its governing documents, and the owner of record when it passes is responsible for paying it. This is why reserve funding matters so much before you buy. An association with thin reserves and visible deferred maintenance is telling you an assessment is coming, even if no vote has been scheduled and nothing appears on the current disclosure.
Get a read on the project before you go under contract
Send us the HOA documents and the property address, and we will give you a free read on whether the project will finance, before you go under contract. Budget, reserve study, litigation disclosure, meeting minutes: send whatever you have, and if you only have the address we will tell you what to ask the listing agent for.
It takes a short review to flag the things that turn into a problem in week three, and it costs you nothing. Call (303) 779-0591 or start at mortgage-maestro.com. If the building is solid, you will move forward with confidence. If it is not, you will find out while walking away is still free.
Mortgage Maestro Group is a veteran-owned independent mortgage brokerage headquartered in Denver, Colorado. NMLS #1838215. Licensed in Colorado, California, Wyoming, Texas, and Florida. Equal Housing Opportunity.