For immediate release October 30, 2026
Zillow down payment assistance can cover an eligible buyer’s FHA down payment, but it is conditional assistance, not an unconditional gift. Before accepting it, compare the cash you need today, the payment you can sustain and what happens if your plans change.
For a Denver first-time buyer, keeping savings available can matter. So can avoiding an obligation that complicates a move or refinance. My perspective as an independent mortgage broker is simple: understand the whole financing arrangement before deciding whether the help fits your life.
What Zillow down payment assistance provides
Zillow describes assistance of up to 3.5% of the lesser of the purchase price or appraised value. It is a zero-interest second mortgage with no monthly payments, paired with an eligible FHA loan through Zillow Home Loans. Colorado is included in its advertised availability.
The company’s official program explanation says the money covers the down payment, not closing costs. Still, those costs need a funding plan. In addition, eligibility includes a minimum 640 credit score, and qualifying remains subject to underwriting.
For context, HUD explains FHA financing separately from any lender’s assistance program. Also, an FHA mortgage still carries mortgage insurance. Assistance does not remove that expense or establish that the purchase is affordable.
What happens to Zillow down payment assistance if you sell, refinance or move?
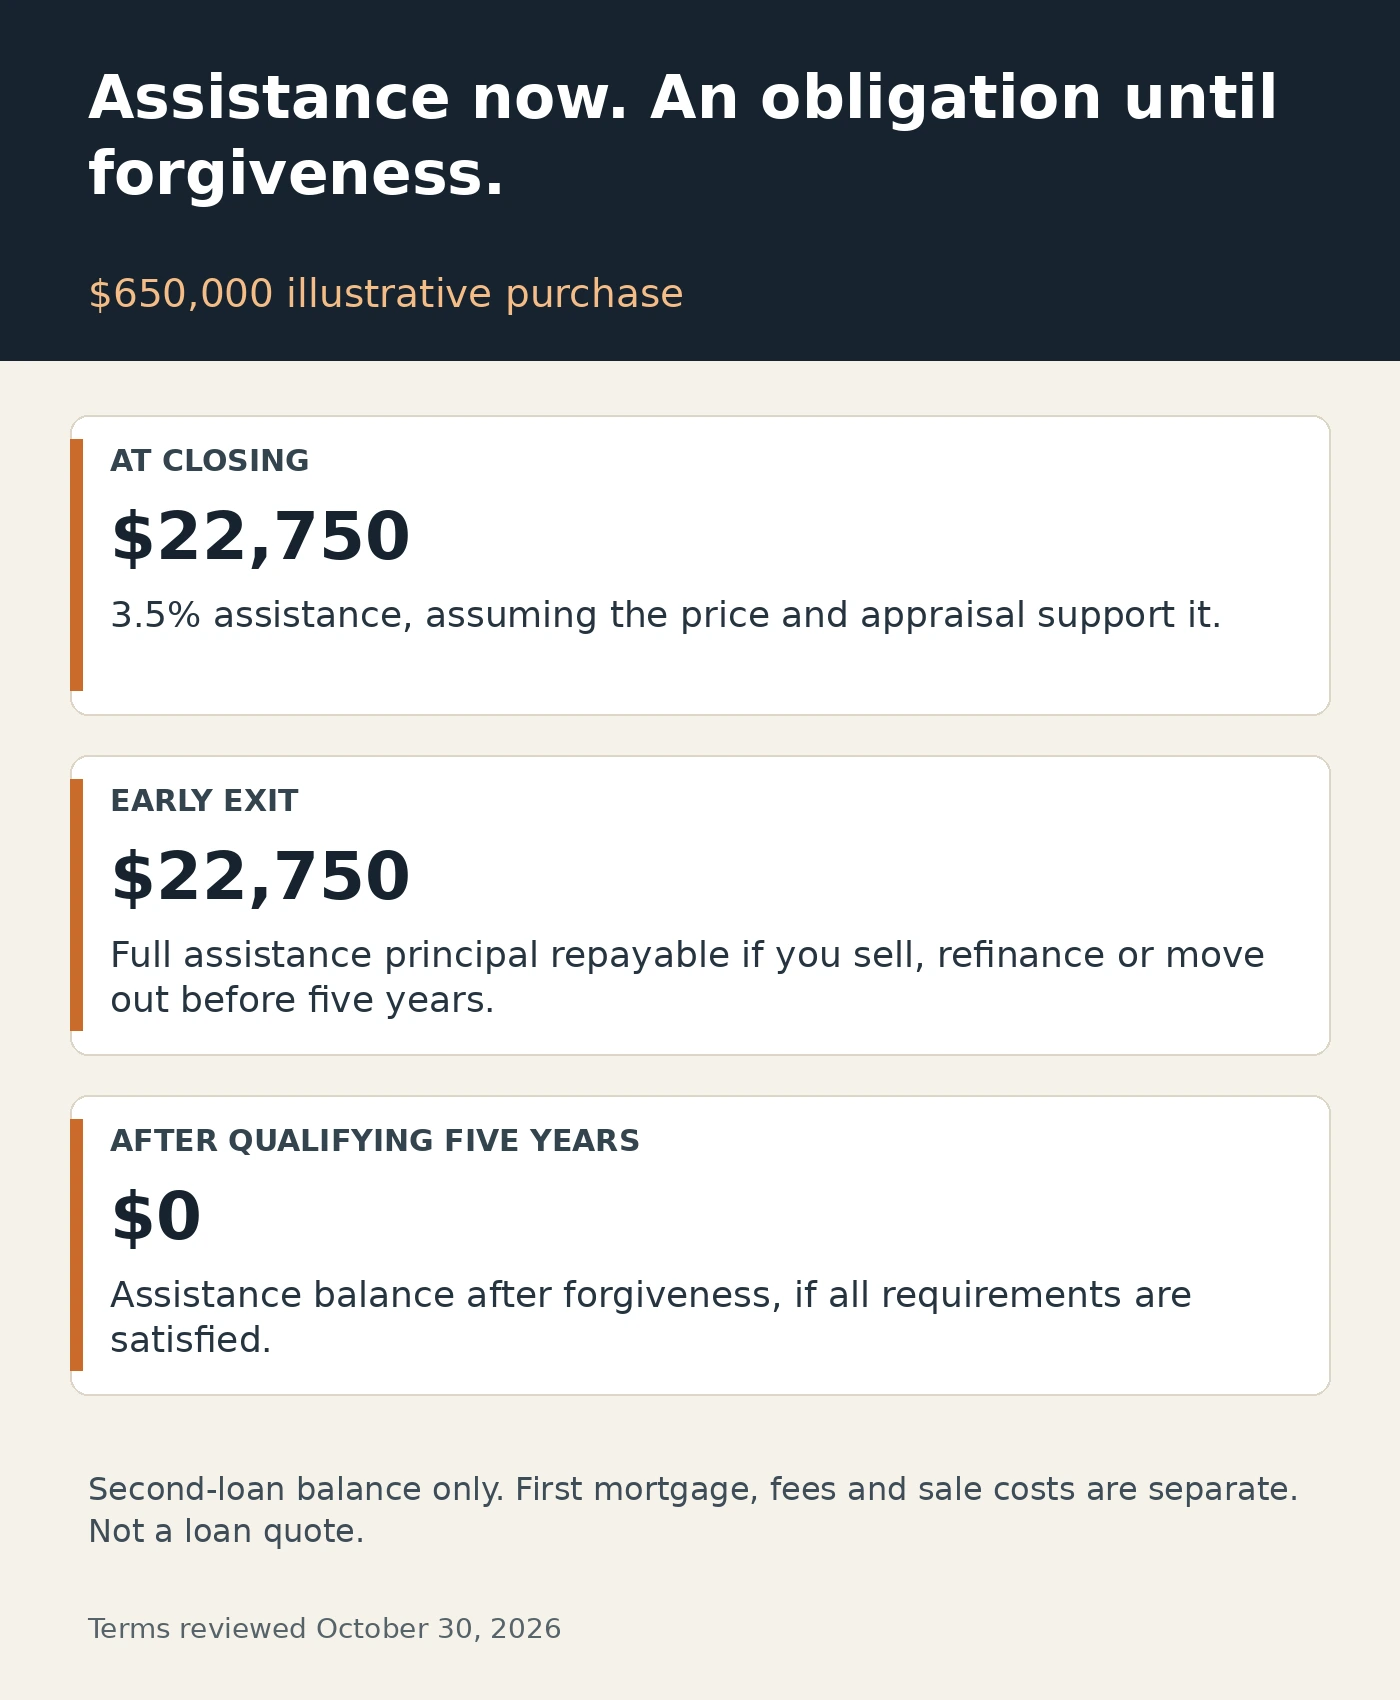
According to Zillow’s program announcement, forgiveness requires five years of on-time mortgage payments and owner occupancy. Selling, refinancing or moving out before that period ends requires full repayment of the assistance.
That is a planning consideration, not an automatic reason to decline. A refinance might still improve your position after repayment. Conversely, a job relocation could make the obligation relevant sooner than expected.
Therefore, request the actual assistance note and forgiveness agreement. Ask how payment problems affect forgiveness, how payoff works and how the lien is released. A marketing summary cannot answer every contractual question.
Zillow down payment assistance: the $650,000 comparison I walked through
In my video, I used a $650,000 purchase to compare the appeal of a covered down payment with the ongoing cost of financing. At 3.5%, the assistance illustration is $22,750, assuming the appraisal supports the price and the buyer qualifies.
The live walkthrough moved from down payment help to interest rates, points, upfront expenses and monthly payments. Around 2:25, I examined FHA financing; around 2:59, I compared payments and upfront costs. That sequence matters: the amount offered at closing is only the beginning of the analysis.
Context for the recording: some pricing inputs came from estimates, including AI-generated estimates, rather than a written Zillow assistance quote. The 6.625% example I discussed was the rate on the day I recorded the video. Rates change often, so it is not a current offer. The video’s estimated cost differences should not be treated as verified lender-specific savings. This article uses verified program terms and does not declare a pricing winner.
Follow both loan balances, not just the payment
In that purchase illustration, a 3.5% down payment leaves a $627,250 base first mortgage before financed upfront mortgage insurance. With assistance, the separate $22,750 second mortgage also exists until repayment or qualifying forgiveness.
If you exit after three years, the assistance principal is still $22,750, assuming no earlier payoff. After completed qualifying forgiveness, it is zero. The first mortgage continues separately. Its remaining balance depends on the actual loan terms and payments.
Compare Zillow down payment assistance, CHFA and metroDPA
The reason to explore alternatives is straightforward: another financing structure may produce lower borrowing costs while still helping you buy. Compare Zillow with CHFA, metroDPA and an own-funded down payment using matched written quotes. None is automatically cheaper, and assistance percentages may use different calculation bases.
CHFA: distinguish the grant from the second mortgage
CHFA’s assistance options pair with a CHFA first mortgage and can help with the down payment or closing costs. Its standard grant offers up to the lesser of $25,000 or 3% of the first mortgage, with no repayment required.
CHFA’s standard second mortgage is a silent second: repayment is deferred rather than collected through a regular monthly payment. It offers up to the lesser of $25,000 or 4% of the first mortgage. Specified events, including sale, refinance, first-mortgage payoff or leaving the home as your primary residence, trigger repayment. Certain specialized programs have different limits.
CHFA discloses higher rates for its assistance options; that does not establish whether a CHFA offer costs more or less than Zillow’s. Instead, compare actual pricing and repayment terms. Likewise, the separate grant and silent second can produce different results.
metroDPA: verify the assistance option and property location
The current metroDPA program website describes a 30-year, zero-interest second mortgage with no scheduled payments. Assistance can support the down payment, closing costs, prepaids or principal reduction, alongside eligible first-mortgage options.
Additionally, it serves eligible Colorado locations and is not restricted to first-time buyers. Income, credit, property and homebuyer-education requirements apply.
Do not assume that no monthly payment means forgiveness. Obtain the current assistance amount, note, maturity and sale/refinance repayment provisions from an approved lender. Those details must match the specific option being reserved; the public overview does not settle every payoff question.
Put the options on the same comparison sheet
Look for the lowest suitable borrowing cost across interest, fees, mortgage insurance and assistance obligations, while preserving adequate reserves. The table below is a decision checklist, not a quote or a promise of availability.
| Compare | What to request |
|---|---|
| Cash to close | Down payment, closing costs, prepaid expenses and credits after assistance. Zillow assistance is for the down payment; CHFA and metroDPA can address additional eligible costs. |
| Monthly housing cost | Principal, interest, mortgage insurance, property taxes, homeowners insurance and HOA charges for each offer. |
| Fees and pricing | Rate, APR, discount points, lender fees, credits and matching lock periods. Do not assume an assistance rate premium. |
| Savings remaining | Actual cash reserves after closing, moving and immediate repairs. |
| Repayment | Zillow’s conditional five-year forgiveness; CHFA grant versus repayable second; metroDPA’s specific note and payoff provisions. |
| Ownership timeline | First- and second-loan balances, fees and forgiveness status if you sell or refinance at years three, five and seven. |
When preserving savings can justify assistance
In practice, using every available dollar for a down payment can leave a household exposed to repairs or interrupted income. Assistance may be valuable when it preserves a useful emergency cushion and the full housing payment remains comfortable.
However, money retained is not automatically money saved. Compare interest, fees, mortgage insurance, assistance repayment and remaining balances over your likely ownership period. Separately consider the value of accessible reserves. That produces a more useful answer than subtracting one advertised benefit from another lender’s estimated costs.
Our FHA loan overview and Denver FHA guide explain the broader financing considerations.
Bring these documents to your mortgage comparison
First, bring current Loan Estimates, rate-lock terms, assistance agreements, a realistic monthly budget and your expected cash reserves. Also explain whether a move, career change or refinance could occur within five years.
Ask each lender to explain which terms are confirmed, which remain estimates and what changes if your plans do. Our guide to when to shop mortgage lenders can help you organize that process.
At Mortgage Maestro Group, the purpose of this conversation is to compare the options against your situation. Zillow down payment assistance can be useful. The right choice should make sense beyond closing day.
Let’s compare your homebuying options
Program terms reviewed October 30, 2026. Educational information, not a loan commitment or rate quote. Eligibility, availability, pricing and terms may change. Illustrations assume qualification and do not include every financing or transaction cost. Mortgage Maestro Group is independent of the named program providers.